The published boundary is four units.
The federal private mortgage-insurance rules define an eligible home property as one to four units. This is not a ban on every loan for a larger building. [2]
Report · Published
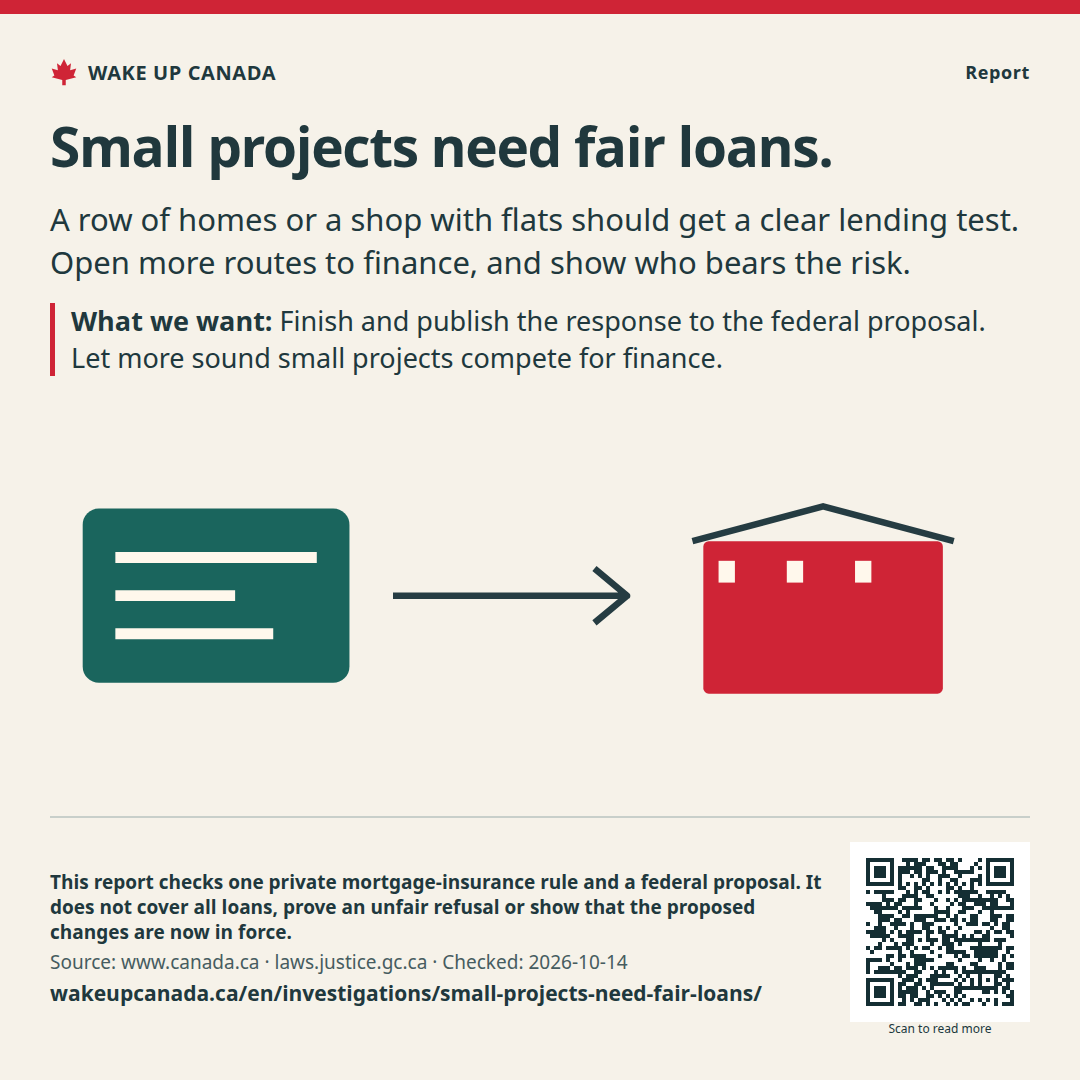
A row of homes or a shop with flats should get a clear lending test. Open more routes to finance, and show who bears the risk.
The federal private mortgage-insurance rules define an eligible home property as one to four units. This is not a ban on every loan for a larger building. [2]
Finance Canada sought views on private insurance for five-to-eight-unit buildings and more scope for new three- and four-unit homes. The comment window ended on July 2, 2026. [1]
We want more people to build, rent and own. A sound small project should not need a big firm’s clout to get a fair hearing. Finance must fit the homes and shops we want, with clear terms and a real check on risk.
The published regulation we checked is current to September 21, 2026. Its one-to-four-unit boundary helps define which loans can use this insurance route. Other routes can exist. It does not tell us their price or whether a given project qualifies.
[2]The June 2026 proposal aims to add private insurer choice for five-to-eight-unit homes. It also aims to help people finance new three- and four-unit homes.
We support opening these routes. Publish the final rules, start date and who can apply. Then show loan terms, use and losses. The closed comment page is not proof the change has taken effect.
[1]Our wider ask includes homes for sale, rental buildings, shops and mixed-use sites. A building with shops below and homes above needs a clear route too. This federal proposal alone does not settle those loans.
Publish the cash needed up front, each payment stage, fees, security and reasons for refusal. Test the gap when a factory needs payment before a home reaches its site. Match real offers for the same project before claiming savings.
Some projects should be refused. Bad budgets, weak demand and cost overruns can hurt borrowers and lenders. More competition is not a promise of cheap money for every plan. Public backing must have a loss budget. Do not hide risk in a guarantee.
Finish and publish the response to the federal proposal. Let more sound small projects compete for finance.
Require a simple cost and payment sheet. Show why a loan was refused and how the applicant can seek a fresh review.
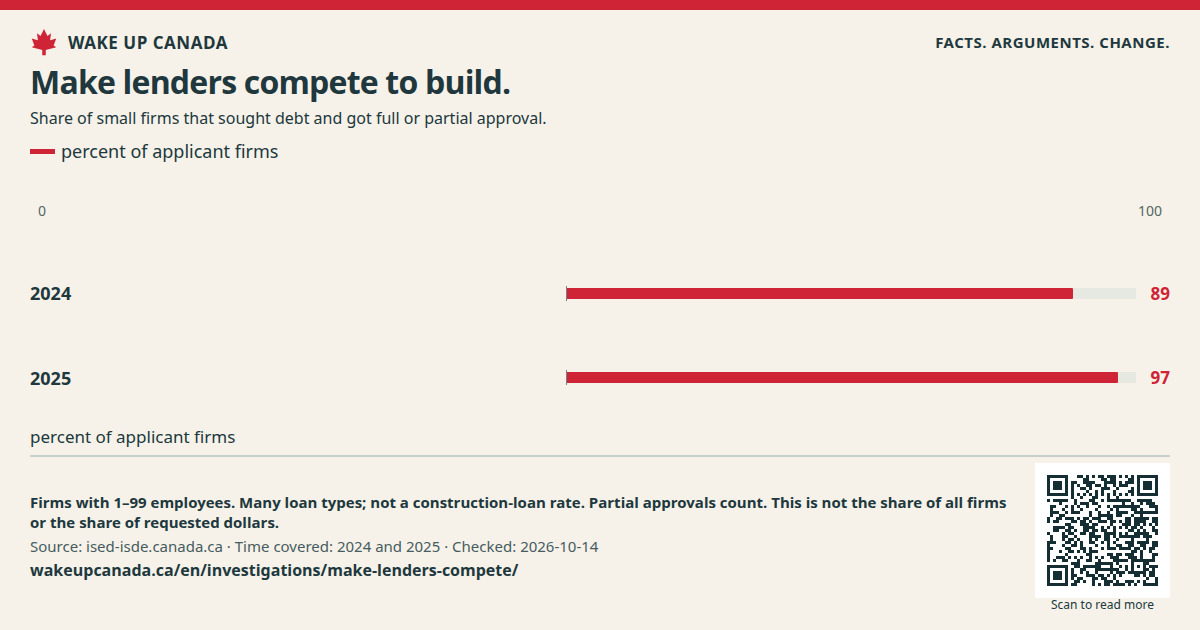
Publish loan results by project size and type. Include firms that gave up before applying. Separate homes, shops and mixed-use sites.
Federal finance officials and mortgage insurers; banks, credit unions and other lenders; provincial land and lending rule makers.
Private lending is not free of risk. Any new public guarantee needs a priced loss budget, clear fees and a cap. We have not priced that plan.
Source title in English
WAKE UP CANADA
Help more people see the facts and the plan.

A row of homes or a shop with flats should get a clear lending test. Open more routes to finance, and show who bears the risk.
Keep the source, date and notes with the image.
Checked:
What this does not show: This report checks one private mortgage-insurance rule and a federal proposal. It does not cover all loans, prove an unfair refusal or show that the proposed changes are now in force.
No account needed. Sharing does not sign you up for email.

If the image opens in a new tab, press and hold it or use your browser’s save tool.
This supports the whole cause. Emails are a separate choice.
Support totals are not available right now.
Each email counts once per cause. This does not sign a petition. Your name and email stay private. Only the total is public.
Banks & loans · Report
Good homes and shops need loans to get built. Builders should be able to compare clear offers and take their plans to a rival lender.
Read the report ↗Homes & neighbourhoods · Report
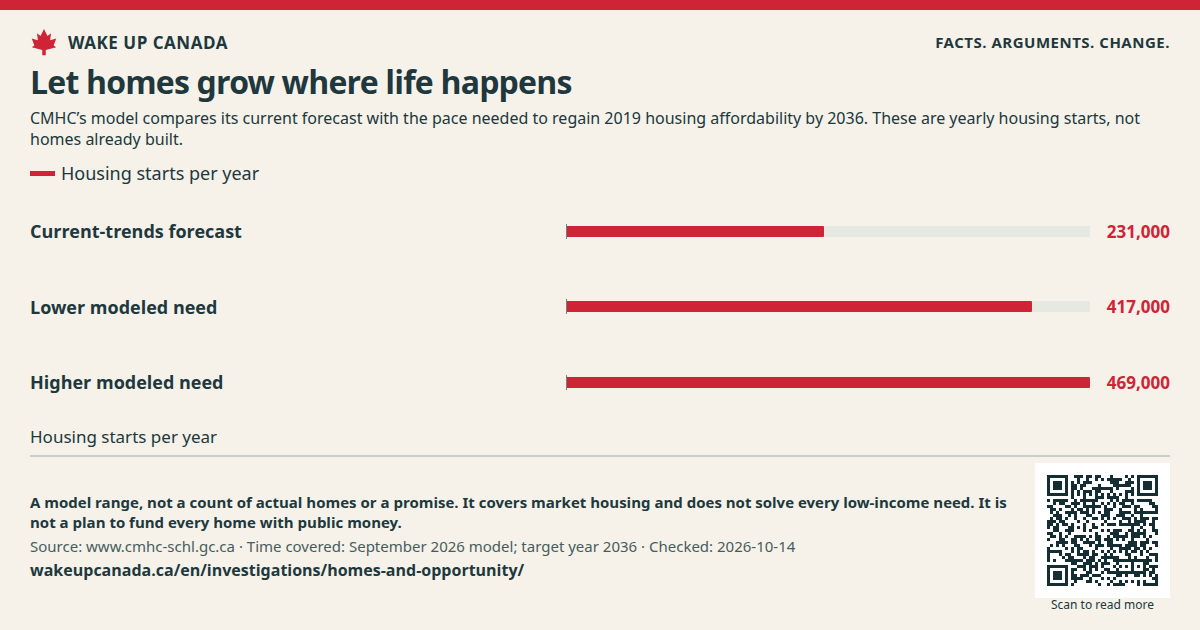
Open the door to useful homes, short trips and more choice. Keep the housing evidence honest.
Read the report ↗Imports & open trade · Report
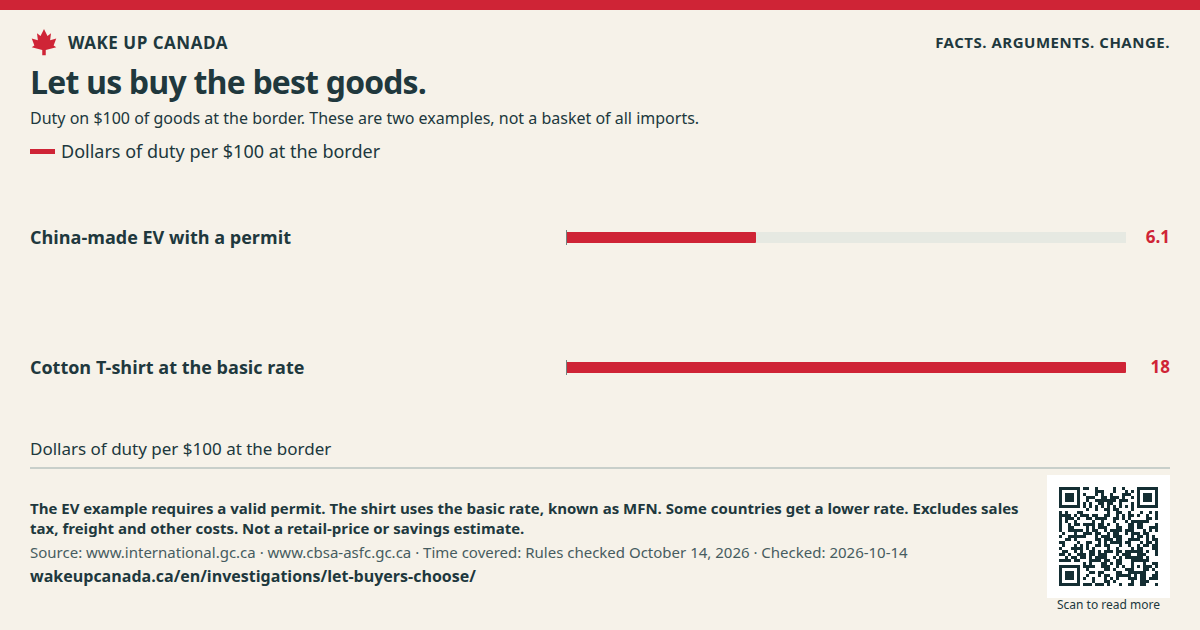
A low price should be good news. Canada should let safe goods compete, no matter where they are made.
Read the report ↗