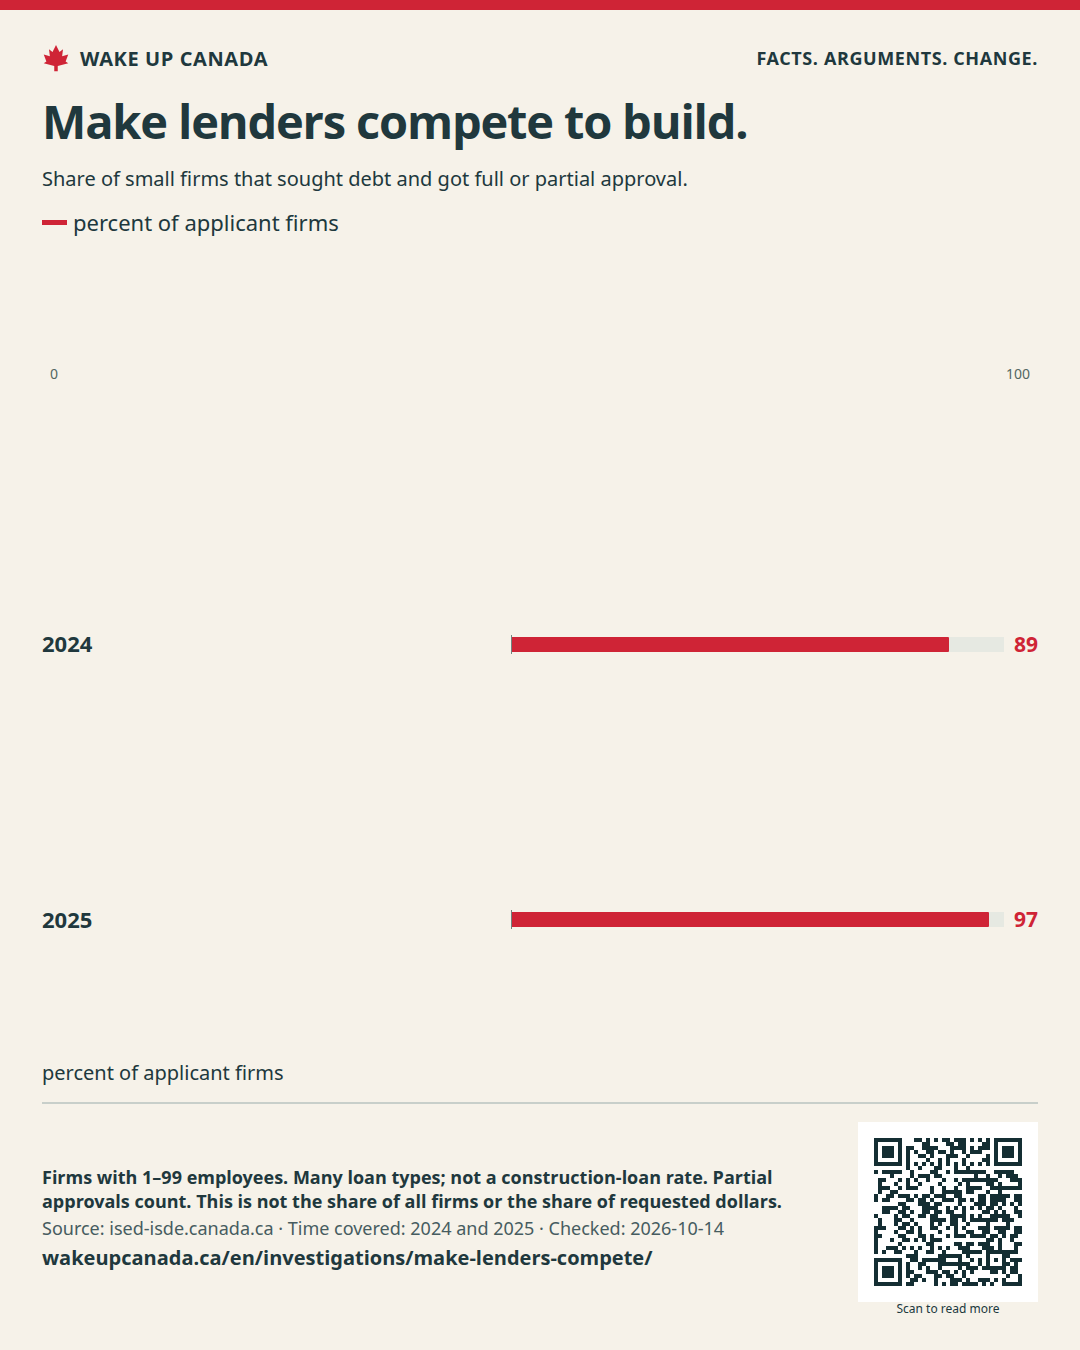
Most small firms that applied got some credit.
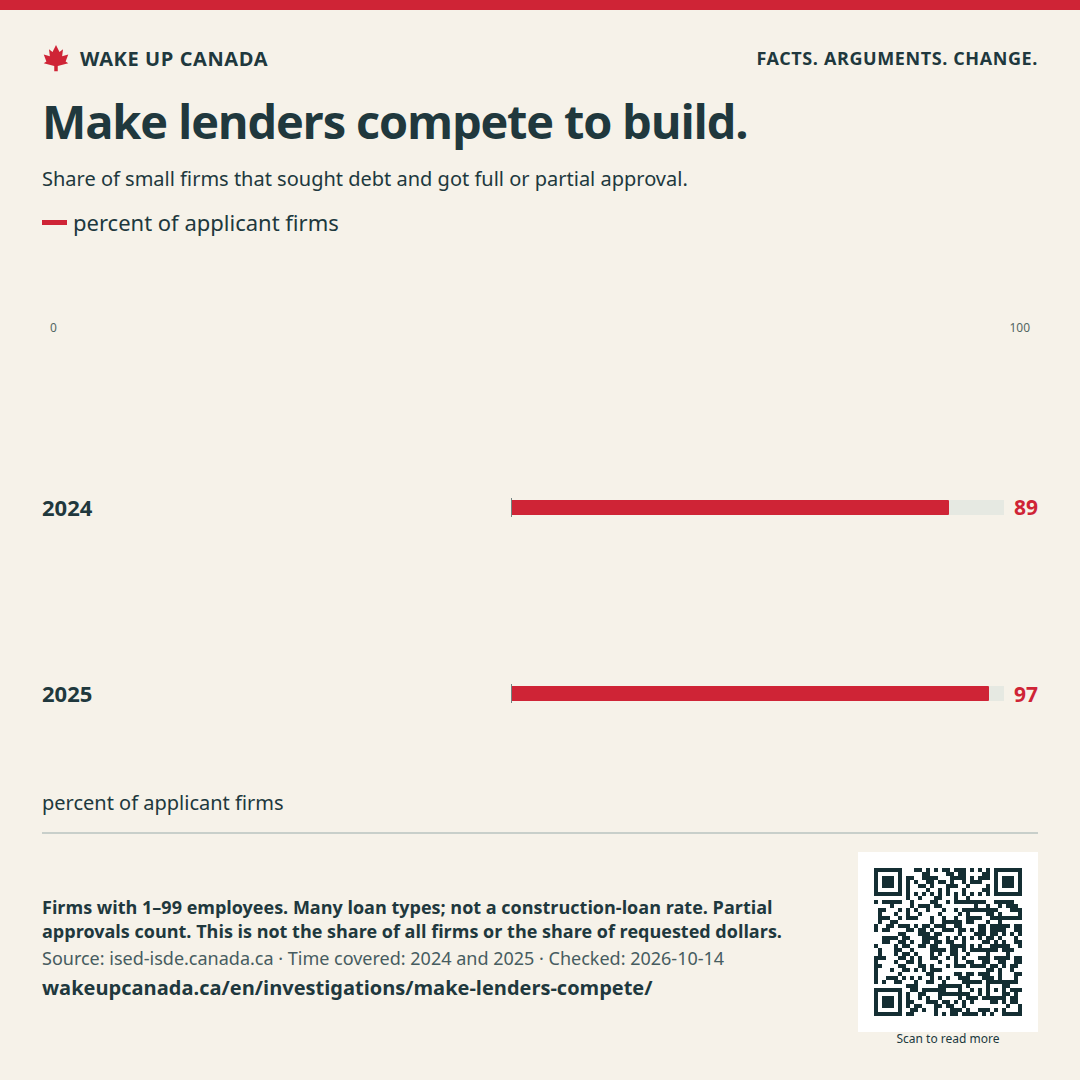
In 2025, 97% of small firms that sought debt got full or partial approval. That rose from 89% in 2024. [1]
Report · Published
Good homes and shops need loans to get built. Builders should be able to compare clear offers and take their plans to a rival lender.
In 2025, 97% of small firms that sought debt got full or partial approval. That rose from 89% in 2024. [1]
Only 20% of small firms sought debt in 2025. The approval rate counts firms that asked. It does not cover every firm. [1]
More lender choice can help good projects get built. Keep sound risk checks, make loan terms clear, and test where finance breaks down.
Only 20% of small firms sought debt in 2025. The 97% approval rate counts firms that got all or some of what they asked for. It does not mean 97% of all firms got a loan.
These results cover firms with 1 to 99 staff and many kinds of debt. They do not isolate loans to build homes or shops. A high approval rate can coexist with gaps for some builders. It cannot prove those gaps on its own.
[1]CMHC’s main apartment construction loan program covers eligible rental projects with at least five units. Its minimum loan is $1 million. It can lend up to the full cost of the rental part and up to 75% of the non-housing part. Those are limits, not a promise to fund each project.
A four-unit rental does not meet this program’s size rule. That does not mean no other loan route exists. We need clear paths for small rentals, homes to buy, factory-built homes and shops. Each needs its own test of fees, delays and risk.
[2]Andrew Graham’s Build Canada memo calls for people to control their bank data. We share that goal. People should be able to share records safely with a rival lender, then compare the full cost.
The Competition Bureau launched a small-business loan study in January 2026. It looks at new lenders and how firms switch loans. It is not proof of wrongdoing. Loans to build homes and shops need a clear place in the work that follows.
[3][4]Failed loans can hurt savers, borrowers and the public. Some projects should be refused. The goal is fair access to sound loans, with clear reasons for a no. It is not a right to make someone else bear every risk.
Finance officials should set a plain loan-cost sheet. Show rates, all fees, required assets, cash-release rules and the cost to switch.
CMHC and bank rule makers should show results by project type and size. Show waits, partial offers and reasons for a no. Any public loan backing needs a loss cap and a clear budget.
Ottawa sets bank rules. Each province sets rules for credit unions under its control. CMHC and lenders can change how they offer loans.
Clear reports and loan rules have a cost to run. We have not priced it. Any new public loan backing needs a budget and a cap on losses.
Share of small firms that sought debt and got full or partial approval.
percent of applicant firms · 2024 and 2025
Firms with 1–99 employees. Many loan types; not a construction-loan rate. Partial approvals count. This is not the share of all firms or the share of requested dollars.
Check the sources: Small Business Credit Condition Trends, 2015–2025
Source title in English
WAKE UP CANADA
Help more people see the facts and the plan.
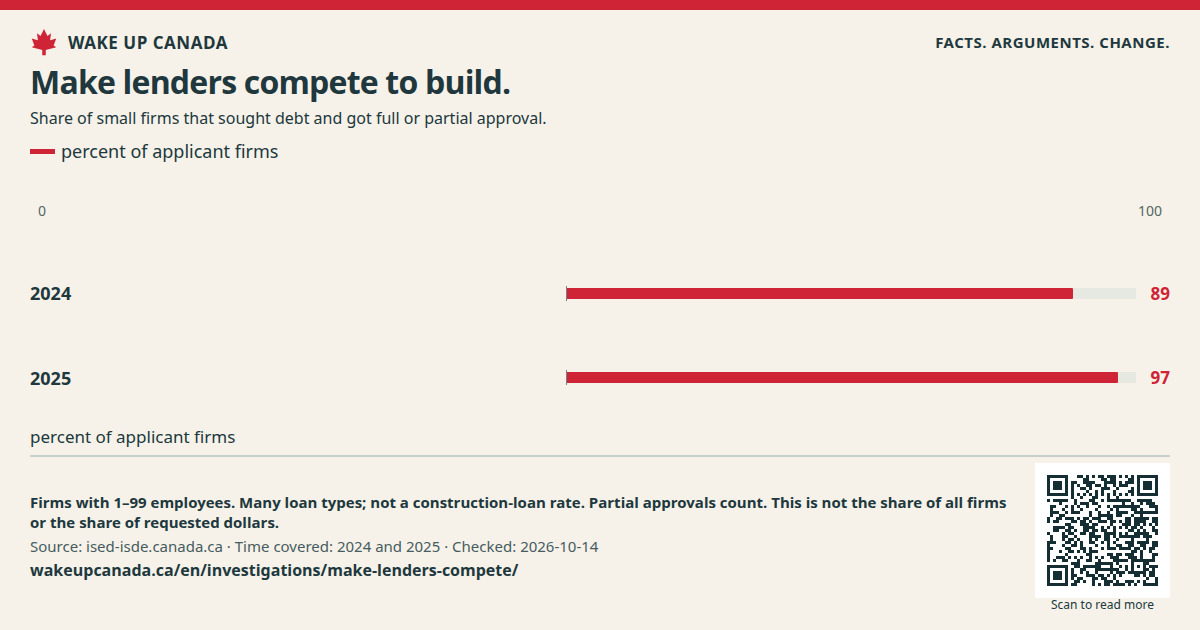
Good homes and shops need loans to get built. Builders should be able to compare clear offers and take their plans to a rival lender.
Keep the source, date and notes with the image.
Checked:
What this does not show: We do not know how many sound building plans lack a loan. Price any new public loan backing before it starts.
No account needed. Sharing does not sign you up for email.

If the image opens in a new tab, press and hold it or use your browser’s save tool.
This supports the whole cause. Emails are a separate choice.
Support totals are not available right now.
Each email counts once per cause. This does not sign a petition. Your name and email stay private. Only the total is public.
Homes & neighbourhoods · Report
Open the door to useful homes, short trips and more choice. Keep the housing evidence honest.
Read the report ↗Imports & open trade · Report
A low price should be good news. Canada should let safe goods compete, no matter where they are made.
Read the report ↗Energy & nature · Report
Cheap power should stay cheap when we count the wires, waste and cleanup. The public should not get a hidden bill.
Read the report ↗